

Autodesk (ADSK) is a subscription software company serving architects, engineers, builders, manufacturers and media creators through products such as AutoCAD, Revit, Fusion, Forma and Maya. Architecture, engineering, construction and operations remain the largest revenue engine, while manufacturing, cloud collaboration, operations software and AI are becoming more important to long-term growth. That breadth creates several paths to expansion, but also leaves ADSK sensitive to construction cycles, software competition and acquisition execution.
Its latest quarter showed durable demand alongside a more complicated forward setup. Autodesk Q2 FY2027 revenue reached $2.046 billion, up 16% year over year, non-GAAP EPS rose $0.68 to $3.30 and free cash flow increased 24% to $561 million. Management raised annual revenue growth guidance to about 16%, though the $3.065 midpoint of Q3 non-GAAP EPS guidance remained roughly $0.08 below consensus as MaintainX costs entered the outlook.
The ADSK stock forecast for 2026 now centers on two competing views:
- The connected-platform and AI adoption case: Autodesk AI, Forma, Fusion and construction workflows could connect more design, make and operate data, while the $3.6 billion MaintainX acquisition extends the platform into asset maintenance and supports a larger recurring-revenue opportunity.
- The integration and execution case: MaintainX dilution, softer billings growth and lower near-term EPS guidance could delay operating leverage, while faster-moving AI design tools challenge pricing and user engagement across established products.
This guide breaks down the ADSK stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Autodesk's August 27, 2026 Q2 FY2027 earnings release, quarterly filing and market data through September 23, plus how to trade ADSK stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Autodesk Investors to Know in September 2026
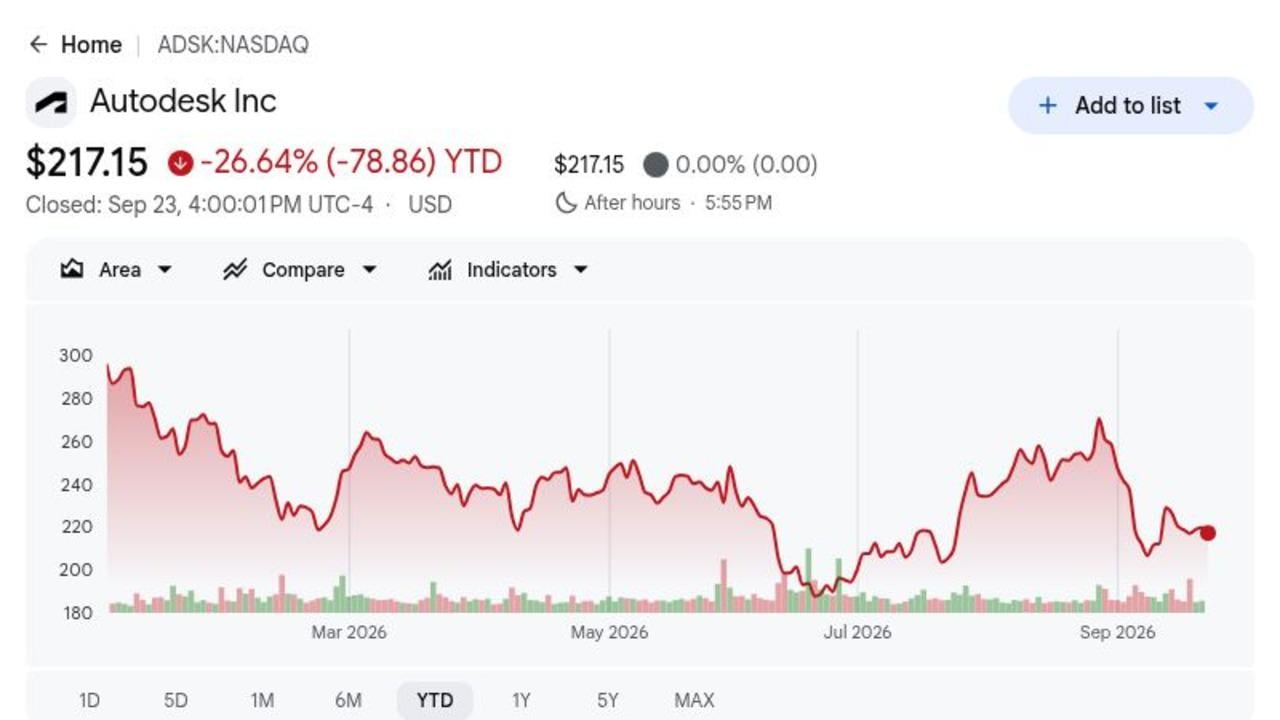
- ADSK closed at $217.15 and was down 26.64% in 2026: The September 23 close remained about 33% below the $326.35 52-week high despite a quarterly beat. The gap shows investors still want clearer proof that AI investment and acquisition spending can translate into stronger per-share earnings.
- Q2 revenue reached $2.046 billion, up 16%: Revenue beat the roughly $2.01 billion consensus by about $36 million, while subscription revenue increased to $1.952 billion from $1.667 billion. The recurring base remains healthy, though the valuation now depends on whether mid-teens growth can continue.
- AECO revenue rose 17% to $1.029 billion: Autodesk's largest product family generated more than half of quarterly revenue, while current RPO increased 12% to $5.245 billion. Construction and infrastructure demand support visibility, though total RPO growth of 2% was softer as Autodesk reduced multi-year discounts.
- FY2027 revenue guidance increased to $8.295 billion to $8.345 billion: The range implies roughly 16% growth and includes MaintainX, while non-GAAP EPS is expected at $12.52 to $12.60. Stronger demand supports the higher sales outlook, but acquisition costs make the earnings path less straightforward.
- The $3.6 billion MaintainX deal expands Autodesk into operations: MaintainX brings an estimated $135 million ARR base growing more than 50%, but Autodesk also narrowed free-cash-flow guidance to $2.725 billion to $2.750 billion and included about $45 million of transaction costs. Integration quality will determine whether the deal creates meaningful per-share value.
What Is Autodesk (ADSK)?
Autodesk is a global design-and-make software company whose products support the full lifecycle of buildings, infrastructure, manufactured goods and digital content. AutoCAD provides general computer-aided design, Revit supports building information modeling, Fusion combines product design and manufacturing, and Maya and 3ds Max serve media and entertainment. Most revenue comes from subscriptions, so renewals, seat expansion, usage and pricing are the main economic drivers. The company also sells cloud collaboration and construction workflows that connect office design teams with field execution.
Autodesk's long-term direction is to converge design, make and operate data across Forma, Fusion and Flow industry clouds, with Autodesk AI adding assistants, automation and project intelligence. Autodesk Construction Cloud links architects, contractors and owners, while partnerships with major cloud and hardware ecosystems support data exchange and compute-intensive workflows. The planned $3.6 billion MaintainX acquisition extends that strategy into maintenance and frontline operations, connecting assets after construction or manufacturing. Management expects this broader platform to deepen customer relationships, though integration and disciplined monetization remain essential.
Read More: Adobe (ADBE) Price Prediction 2026: Can AI Monetization Push ADBE Toward $350?
Autodesk (ADSK) Q2 FY2027 Earnings Overview: Revenue and Margin Growth Strengthen the FY2027 Outlook
Autodesk delivered Q2 revenue of $2.046 billion versus $2.01 billion expected, non-GAAP EPS of $3.30 versus $3.12 expected, GAAP net income of $492 million and free cash flow of $561 million. AECO revenue grew 17% to $1.029 billion and current RPO increased 12% to $5.245 billion. Management raised FY2027 revenue to $8.295 billion to $8.345 billion, although the $3.065 Q3 EPS midpoint trailed consensus and highlighted MaintainX dilution.
Read More: Autodesk (ADSK) Q2 FY2027 Earnings: $2.05B Revenue Beat but MaintainX Dilution Weighs on Shares
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 FY2027 revenue |
$2.01B consensus |
$2.046B |
Beat. About $36M above consensus and up 16% YoY. |
|
Q2 non-GAAP diluted EPS |
$3.12 consensus |
$3.30 |
Beat. $0.18 above consensus and up $0.68 YoY. |
|
Q2 GAAP diluted EPS |
$1.46 one year earlier |
$2.33 |
Improved. Increased $0.87 YoY. |
|
Q2 GAAP net income |
$313M one year earlier |
$492M |
Improved. Increased 57% YoY. |
|
Q2 billings |
— |
$1.854B |
Grew. Increased 10% YoY. |
|
Q2 AECO revenue |
— |
$1.029B |
Grew. Increased 17% YoY and 15% in constant currency. |
|
Q2 current RPO |
— |
$5.245B |
Expanded. Increased 12% YoY. |
|
Q2 non-GAAP operating margin |
39% one year earlier |
41% |
Expanded. Improved 2 percentage points YoY. |
|
Q2 free cash flow |
$452M one year earlier |
$561M |
Grew. Increased 24% YoY. |
|
Q3 FY2027 revenue outlook |
$2.08B consensus |
2.125B–2.140B |
Above. The $2.133B midpoint exceeded consensus by about $53M. |
|
Q3 non-GAAP EPS outlook |
$3.14 consensus |
3.04–3.09 |
Below. The $3.065 midpoint trailed consensus by about $0.08. |
|
FY2027 revenue outlook |
Prior growth outlook of 15% |
8.295B–8.345B |
Raised. The new range implies about 16% growth. |
|
FY2027 free cash flow outlook |
Prior range above new midpoint |
2.725B–2.750B |
Narrowed. Includes about $45M of MaintainX transaction expense. |
- Revenue of $2.046 billion beat consensus by about $36 million: Sales grew 16% year over year versus 14% in constant currency, while subscription revenue reached $1.952 billion. The result shows that renewals and cloud adoption continue to support durable growth.
- Non-GAAP EPS of $3.30 beat consensus by $0.18: GAAP EPS increased to $2.33 from $1.46, while net income rose 57% to $492 million. Profit grew faster than revenue as operating leverage and lower restructuring costs improved earnings conversion.
- AECO revenue reached $1.029 billion and grew 17%: Make revenue rose 26% to $244 million, while AutoCAD increased 14% to $500 million. Growth across major product groups reduces dependence on a single application and supports Autodesk's broader platform strategy.
- Free cash flow rose 24% to $561 million: Cash from operations reached $575 million, while non-GAAP operating margin expanded two points to 41%. The improvement shows stronger underlying economics, though the $2.725 billion to $2.750 billion annual free-cash-flow outlook includes MaintainX financing and transaction costs.
- FY2027 revenue guidance increased, but Q3 EPS guidance missed by about $0.08: Annual revenue now targets $8.295 billion to $8.345 billion, while Q3 non-GAAP EPS of $3.04 to $3.09 remains below the $3.14 consensus. The key question is whether stronger sales growth can offset near-term acquisition dilution.
Read More: Autodesk (ADSK) Q2 FY2027 Earnings: $2.05B Revenue Beat but MaintainX Dilution Weighs on Shares
Autodesk (ADSK) 2026 Investment Outlook: $350 Bull Case vs. $185 Bear Case
Autodesk's 2026 outlook depends on whether steady subscription growth, AI tools, and the MaintainX acquisition can translate into stronger margins and free cash flow. The upside comes from deeper adoption across design, construction, and operations, while integration costs, slower project spending, and software competition remain the main risks.
The Bull Case: Stronger AI and Construction Demand Push ADSK Toward $350
The Bull Case assumes Autodesk sustains revenue growth near the 16% FY2027 outlook as Forma, Fusion, Construction Cloud, and Autodesk AI support more workflows. MaintainX adds an operations layer, while AECO growth above 15% and current RPO growth near 12% preserve forward visibility.
A move toward $350 would require revenue near the top of the $8.295 billion to $8.345 billion range, successful MaintainX integration, and renewed operating leverage after transaction costs. Non-GAAP margin holding near 39% for the year, followed by improvement, would strengthen the case.
The Base Case: Steady Subscription Growth Keeps ADSK Between $260 and $310
The Base Case assumes AutoCAD, Revit, Fusion, and construction subscriptions remain resilient while AI adoption develops gradually. Revenue continues growing in the low-to-mid teens, but total RPO growth near 2%, lower multi-year discounting, and MaintainX expenses limit a faster re-rating.
ADSK could trade mainly between $260 and $310 under these conditions. Q3 revenue within $2.125 billion to $2.140 billion, current RPO growth near 12%, and annual free cash flow above $2.725 billion would support the range. Slower billings or further margin pressure would weaken the upper end.
The Bear Case: Slower Customer Spending and Higher Costs Pull ADSK Toward $185
The Bear Case assumes customers delay projects, AI-native competitors pressure pricing, and MaintainX integration costs last longer than expected. Billings growth falls below the Q2 rate of 10%, current RPO slows, and operating margin fails to recover as sales and development spending rise.
A move toward $185 would become more likely if quarterly revenue misses guidance, free cash flow falls below the $2.725 billion annual floor, or management lowers FY2027 EPS below $12.52. Weaker estimates combined with a lower software valuation would add further pressure.
ADSK Stock Price Forecasts for 2026 By Wall Street Analysts
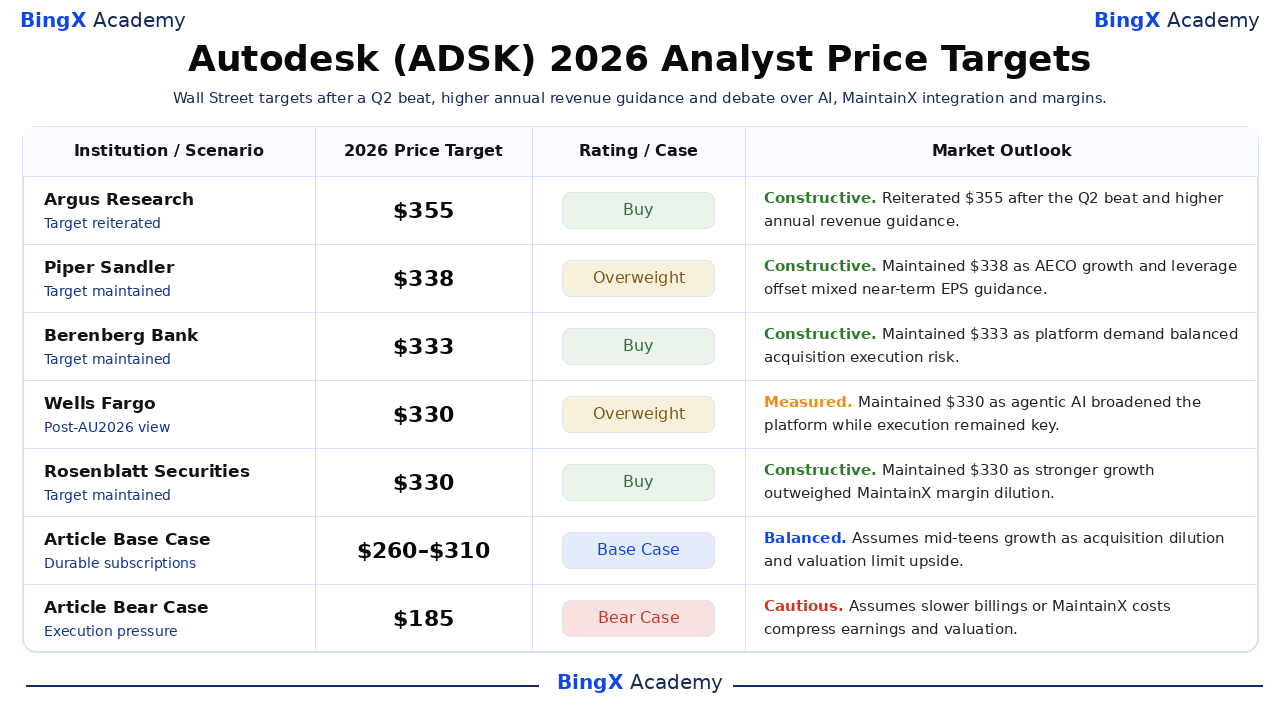
These five dated analyst actions are sorted from highest to lowest. Their spread reflects different views on recurring growth, AI, MaintainX integration and valuation rather than a single promised outcome. The final Base and Bear rows are BingX Academy editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Argus Research |
$355 |
Buy |
Constructive. September 1: reiterated after the Q2 beat as recurring growth and higher annual revenue guidance supported the view. |
|
Piper Sandler / Clarke Jeffries |
$338 |
Overweight |
Constructive. August 28: maintained as AECO growth and leverage balanced mixed near-term EPS guidance. |
|
Berenberg Bank / Nay Soe Naing |
$333 |
Buy |
Constructive. September 1: maintained as platform demand balanced acquisition execution risk. |
|
Wells Fargo / Michael Turrin |
$330 |
Overweight |
Measured. September 18: maintained after Autodesk University as agentic AI broadened the platform while execution remained key. |
|
Rosenblatt Securities / Blair Abernethy |
$330 |
Buy |
Constructive. August 28: maintained as stronger growth outweighed MaintainX margin dilution. |
|
Article Base Case |
260–310 |
Base Case |
Balanced. Assumes mid-teens growth as acquisition dilution and valuation limit upside. |
|
Article Bear Case |
$185 |
Bear Case |
Cautious. Assumes slower billings or MaintainX costs compress earnings and valuation. |
How to Trade Autodesk (ADSK) Stock on BingX
Trade Autodesk's subscription-growth, industry-cloud, AI and MaintainX-integration outlook using BingX TradFi and BingX AI tools. Because ADSK can react sharply to earnings, guidance, acquisition updates and software-sector valuations, traders should define both the catalyst and risk limits before entering a position.
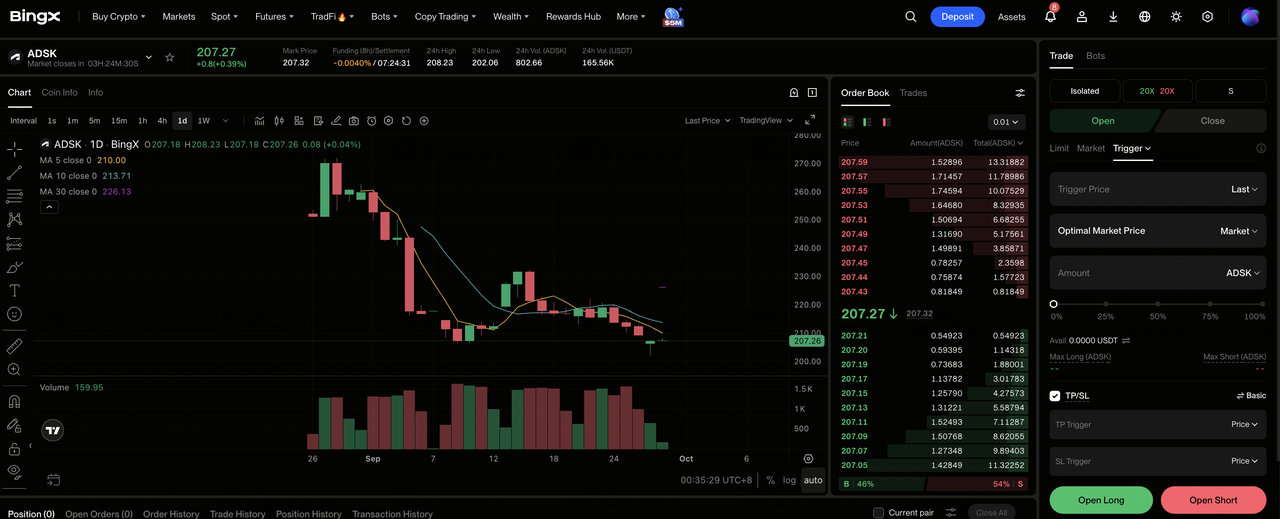
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Autodesk (ADSK). Search for and select the ADSK-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if you expect AI adoption, industry-cloud demand and MaintainX integration to sustain mid-teens growth. Select Open Short if you expect slower billings, margin dilution or software competition to weaken earnings.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 26.64% YTD decline through September 23 shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. ADSK can react quickly to earnings, guidance, analyst revisions, AI product announcements and MaintainX integration updates.
Top 5 Risks to Watch for Autodesk Investors in 2026
Autodesk's outlook depends on recurring demand, platform execution, acquisition discipline, and valuation. Each risk below could weaken future cash flow or reduce the multiple investors are willing to pay.
- MaintainX integration can dilute near-term returns: Autodesk is paying $3.6 billion for a business with about $135 million of annualized recurring revenue. Slower cross-selling, higher retention costs, or transaction expenses above the disclosed $45 million could reduce free cash flow per share.
- AI competition can pressure pricing and seat growth: Autodesk AI can deepen workflows, but lower-cost design tools may reduce seat expansion or make customers question premium subscriptions. Even modest renewal weakness would matter because subscription revenue contributed $1.952 billion of Q2 sales.
- Billings can lag reported revenue: Q2 billings grew 10%, below the 16% revenue growth rate, while total RPO increased only 2%. If current RPO also slows from 12%, future revenue visibility could weaken before reported sales show the same pressure.
- Construction and manufacturing cycles can slow demand: AECO generated $1.029 billion and manufacturing contributed $385 million in Q2. Higher financing costs, delayed projects, or weaker factory investment could reduce new subscriptions and expansion demand.
- Valuation remains sensitive to execution: The $217.15 reference price already reflects a large decline, but still assumes mid-teens growth and strong margins. Revenue below the $8.295 billion annual floor or EPS below $12.52 could pressure both earnings estimates and the valuation multiple.
Final Thoughts: Should You Invest in Autodesk in 2026?
Autodesk's core franchise remains durable: Q2 revenue grew 16% to $2.046 billion, AECO revenue rose 17%, current RPO increased 12% and free cash flow reached $561 million. The company also has a credible long-term strategy connecting design, construction, manufacturing and operations data. The open question is whether the $3.6 billion MaintainX acquisition and expanding AI investment improve per-share economics quickly enough.
The Bull Case reaches $350 if annual revenue lands near the top of guidance, MaintainX cross-selling develops and margins resume expansion. The Bear Case points toward $185 if billings decelerate, integration costs persist or AI competition weakens renewal economics. Conservative traders may wait for Q3 revenue, billings, current RPO and free-cash-flow guidance to confirm which path is taking shape.
Risk Reminder: Trading and investing in equities like ADSK involves a high risk of capital loss. Acquisition execution, software competition, cyclical customer spending, valuation changes and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Adobe (ADBE) Price Prediction 2026: Can AI Monetization Push ADBE Toward $350?
- Palantir (PLTR) Stock Price Prediction 2026: Can 149% U.S. Commercial Growth Push PLTR Toward $255?
- IBM (IBM) Price Prediction 2026: Can Software and Quantum Growth Push IBM Toward $350?
- Figma (FIG) Price Prediction 2026: Can AI Monetization Push FIG Toward $45?
- CrowdStrike (CRWD) Price Prediction 2026: Can AI Security and Falcon Flex Push CRWD Toward $280?
