


Rubrik (RBRK) sells software that protects enterprise data and helps restore systems after cyberattacks. Security Cloud anchors its recurring contracts, while Agent Cloud extends that recovery model to AI agents and their activity. Rising subscriptions create a larger revenue base, but hosting costs, stock compensation and long enterprise sales cycles determine how much of that growth becomes per-share profit.
The latest quarter showed strong recurring demand and improving adjusted earnings, while GAAP profitability remains unfinished. Rubrik fiscal Q2 FY2027 revenue grew 38% to $427.3 million, subscription ARR reached $1.66 billion and adjusted diluted EPS was $0.20. Rubrik still recorded a $61.8 million GAAP loss. The next test is whether large-customer expansion and paid AI security deployments lift cash generation faster than delivery and compensation costs.
The RBRK stock forecast for 2026 now centers on two views:
- The recurring-growth and AI-security case: Customer expansion could lift earnings expectations toward the editorial $150 scenario.
- The costs and valuation case: Slower bookings, dilution and valuation could reduce future-growth expectations.
This guide breaks down the RBRK stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Rubrik’s latest earnings, quarterly filing, product announcements and dated analyst actions, plus how to trade RBRK stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Rubrik Investors to Know in October 2026
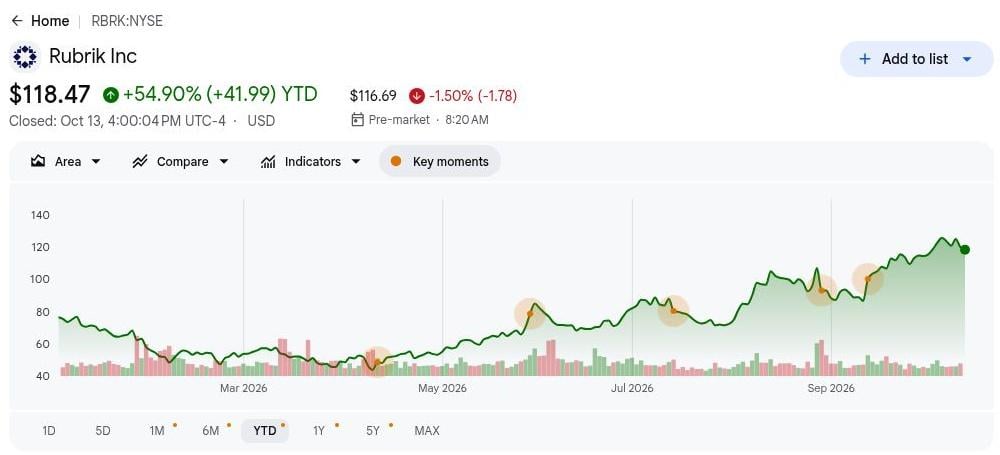
- RBRK closed at $118.47 after gaining 54.90% in 2026. The October 13 NYSE close is near several $120 analyst targets. Investors already anticipate substantial progress. Further gains require cash or growth expectations, with paid adoption providing more reliable confirmation than announcements alone.
- Q2 revenue rose 38% to $427.3 million. Subscription sales contributed $407.2 million, approximately 95% of total revenue, reinforcing the shift toward recurring software. Revenue also exceeded the $396.3 million tracked consensus. Existing deployments support expansion and reduce dependence on new-customer acquisition.
- Cloud ARR grew 39% to $1.48 billion. Adjusted net new Cloud ARR increased 20%, a useful check on growth that excludes migration effects. Migrating existing customers can lift Cloud ARR without equivalent incremental spending. Underlying additions must support the valuation assigned to growth.
- Annual ARR guidance reached $1.880 billion to $1.885 billion. Management also expects $323 million to $333 million of FY2027 free cash flow. These targets support product investment. Recurring growth becomes more valuable when cash expands faster than sales and support spending.
- Rubrik AI reached one-third of global customers in September. September’s adoption announcement and October’s Project Hourglass expansion with AHEAD, Trace3 and WWT establish distribution progress. These routes into enterprise workflows need paid expansion to establish incremental revenue and justify investment.
What Is Rubrik (RBRK)?
Rubrik sells subscription software that protects, monitors and restores data across enterprise systems, public clouds and SaaS applications. Security Cloud combines immutable backups, threat analysis and recovery orchestration so customers can resume clean operations after an attack. The company earns cloud-subscription revenue over contract terms and recognizes some term licenses partly upfront, as its quarterly filing explains. Annual recurring revenue therefore helps show the contracted base when quarterly sales timing changes. Hosting and support costs determine how much of that base reaches profit.
Rubrik is extending its recovery architecture to identities and autonomous applications. Project Hourglass brings Cognizant, Deloitte, LTM, HCLTech, NTT DATA and Wipro into Agent Cloud distribution for Anthropic's Claude Code; Code Guardian adds AHEAD, Trace3 and WWT to services-led deployment. These partners can introduce Rubrik to customers managing AI agents within complex security workflows. Certification and integration take time, however, and the commercial test is whether deployments turn into paid contracts and durable ARR.
Rubrik (RBRK) Q2 FY2027 Earnings Overview: 38% Revenue Growth Beats Estimates
Fiscal Q2 FY2027 revenue grew 38% to $427.3 million, ahead of the $396.3 million consensus reference, and adjusted diluted EPS reached $0.20 versus $0.04 expected. Subscription ARR rose 33% to $1.66 billion, while contribution margin improved to 14.0%. Management raised annual revenue guidance to $1.685 billion to $1.693 billion. Positive cash generation supports expansion, but a $61.8 million GAAP loss keeps the quality of earnings in focus.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q2 FY2027 revenue |
$396.3M consensus |
$427.3M |
Beat. $31.0M above estimate; up 38% YoY. |
|
Non-GAAP diluted EPS |
$0.04 consensus |
$0.20 |
Beat. $0.16 above estimate. |
|
GAAP net loss |
$95.9M loss a year earlier |
$61.8M loss |
Improved. Loss narrowed by $34.1M. |
|
Subscription ARR |
$1.25B a year earlier |
$1.66B |
Expanded. Up 33% year over year. |
|
ARR contribution margin |
9.4% a year earlier |
14.00% |
Improved. Up 4.6 percentage points. |
|
Q3 FY2027 revenue outlook |
Q2 actual $427.3M |
429M–431M |
Higher. $430M midpoint is up $2.7M sequentially. |
|
Free cash flow |
$57.5M a year earlier |
$65.7M |
Improved. Up $8.2M year over year. |
|
Stock-based compensation |
$88.5M a year earlier |
$101.0M |
Higher. Up $12.5M year over year. |
- 38% revenue growth understated normalized demand. Material-rights revenue declined to $4.7 million from $14.2 million, and management reported 43% growth after excluding that effect. This strengthens the underlying demand interpretation. Reported revenue includes upfront licenses, so recognition timing still matters.
- ARR growth of 33% reflected deeper recurring demand. The company ended July with 3,084 customers contributing at least $100,000 of subscription ARR, up 23%. Larger relationships support cross-selling. Additional capabilities must increase contract value enough to offset procurement delays and consolidation discounts.
- Contribution margin of 14.0% improved by 460 basis points. It rose from 9.4%, signaling leverage across recurring contracts. GAAP gross margin nevertheless declined from 79.5% to 78.4%. Delivery economics differ from sales efficiency. Infrastructure costs can rise despite commercial scale.
- Adjusted EPS of $0.20 contrasted with a $61.8 million GAAP loss. The prior-year adjusted result was a $0.03 loss. Quarterly stock compensation reached $101.0 million. Adjusted profits support the model; equity compensation requires monitoring share count.
- Q3 revenue guidance of $429 million to $431 million sets the next hurdle. Contribution margin guidance is 14%; annual cash guidance is $323 million to $333 million. Delivering these targets confirms conversion into cash. Reduced guidance would weaken valuation support before year-end results arrive.
Rubrik (RBRK) 2026 Investment Outlook: $150 Bull Case vs. $90 Bear Case
Rubrik's 2026 outlook depends on whether recurring security demand and new AI products can improve earnings and cash flow together. Large-customer expansion and partner-led distribution support the upside. Slower cloud additions, expensive delivery or limited paid Agent Cloud adoption would leave the stock reliant on a high valuation for future growth rather than current GAAP profit.
The Bull Case: Stronger AI Security Adoption Pushes RBRK Toward $150
The Bull Case assumes ARR maintains growth near or above 33% and adjusted net new Cloud ARR accelerates beyond 20%. Agent Cloud and Code Guardian begin adding paid contracts alongside core recovery software. Larger subscriptions spread sales and engineering expense across a broader base, while cloud delivery costs grow more slowly than contracted revenue.
A move toward $150 would require partner deployments to turn into paid usage, stronger ARR or cash guidance and better contribution margin. Customer demonstrations alone would not confirm the earnings improvement needed to support that target.
The Base Case: Steady Subscription Demand Keeps RBRK Between $110 and $130
The Base Case assumes Rubrik delivers its annual guidance while AI sales build gradually. Core recovery demand remains resilient and Project Hourglass widens distribution, but regulated enterprise buyers take time to deploy new security workflows. Continued GAAP losses and cloud delivery costs limit how much investors pay for the recurring base.
RBRK could trade mainly between $110 and $130 if Q3 sales reach $429 million to $431 million, contribution margin holds near 14% and annual cash guidance remains intact. Weaker cloud additions would challenge the range.
The Bear Case: Slower Bookings and Higher Costs Pull RBRK Toward $90
The Bear Case assumes cloud additions slow and enterprise buyers defer Agent Cloud commitments. Engineering and hosting spending would then precede revenue from newer products, reducing operating leverage despite the established recovery business. Stock compensation would further limit the per-share benefit of any cash improvement.
A move toward $90 would become more likely if ARR or cash guidance falls, large-customer expansion weakens or paid AI conversion disappoints. Lower growth estimates and a reduced valuation multiple would reinforce each other.
RBRK Stock Price Forecasts for 2026 By Wall Street Analysts
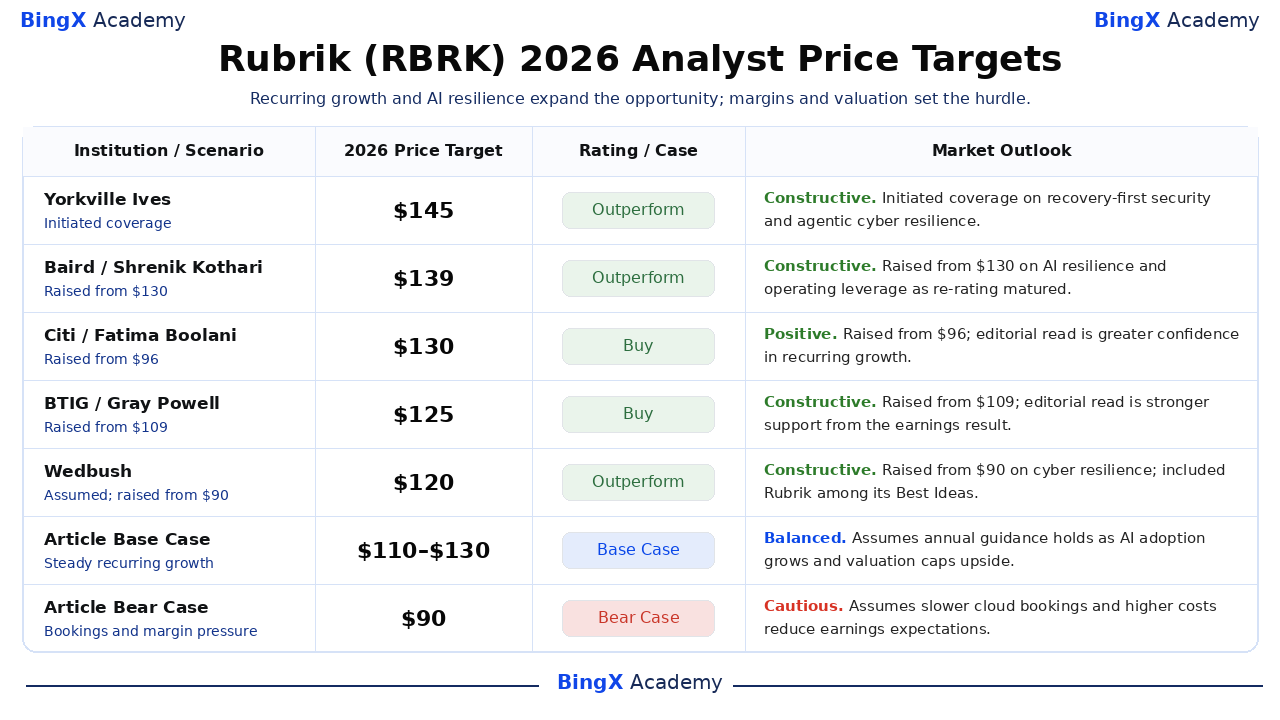
These dated institutional actions were verified through October 14. Rolling 12-month targets extend into 2027; year-end outcomes remain uncertain. Where reports establish only an action, the interpretation is labeled editorial. Article Base and Bear rows are independent scenarios for the remaining calendar year.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Yorkville Ives |
$145 |
Outperform |
Constructive. October 7: Initiated coverage on recovery-first security and agentic cyber resilience; individual analyst not disclosed. |
|
Baird |
$139 |
Outperform |
Constructive. September 23: Raised from $130 on AI resilience and operating leverage as the re-rating opportunity matured. |
|
Citi |
$130 |
Buy |
Positive. August 28: Raised from $96; editorial read is greater confidence in recurring growth. |
|
BTIG |
$125 |
Buy |
Constructive. August 28: Raised from $109; editorial read is stronger support from the earnings result. |
|
Wedbush |
$120 |
Outperform |
Constructive. September 11: Assumed coverage and raised from $90, citing cyber resilience and placing Rubrik on its Best Ideas list. |
|
CIBC |
$120 |
Outperformer |
Measured. August 31: Raised from $115; editorial read is a measured post-earnings valuation reset. |
|
Article Base Case |
$110 to $130 |
Base Case |
Balanced. Assumes annual guidance holds as AI adoption grows and valuation caps upside. |
|
Article Bear Case |
$90 |
Bear Case |
Cautious. Assumes slower cloud bookings and higher costs reduce earnings expectations. |
How to Trade Rubrik (RBRK) Stock on BingX
Trade Rubrik’s recurring growth, AI security adoption and profitability outlook using BingX TradFi and BingX AI tools. Because RBRK can react sharply to ARR updates, guidance and partner announcements, traders should define both the catalyst and risk limits before entering a position.
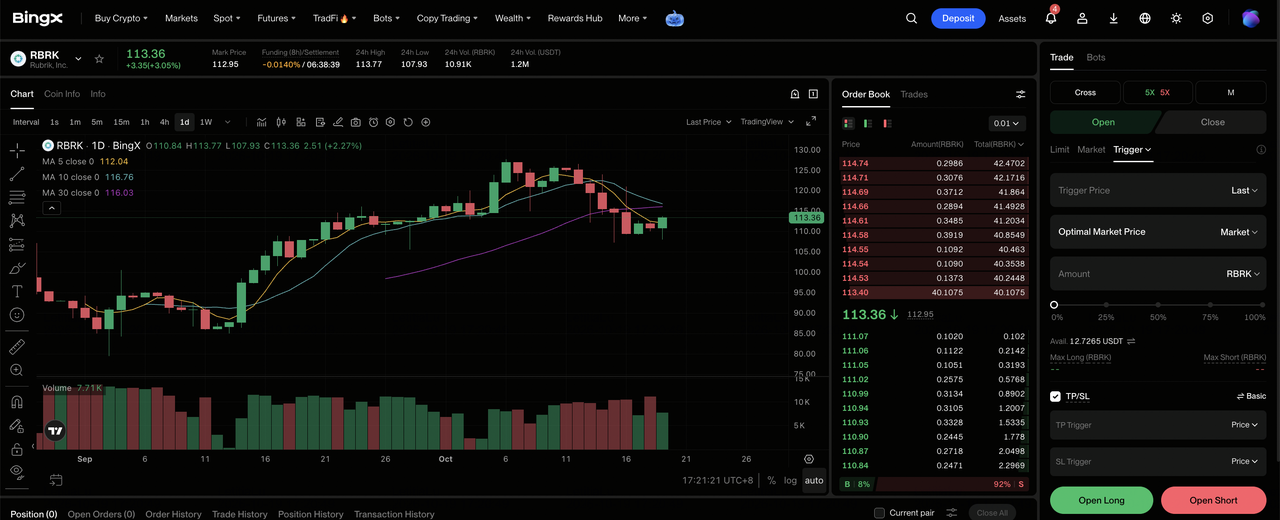
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Rubrik (RBRK). Search for and select the RBRK-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if you expect stronger recurring additions and paid AI adoption to lift guidance. Select Open Short if you expect cloud bookings, cash forecasts or delivery margins to weaken.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. RBRK’s 54.90% year-to-date advance makes conservative leverage and clear position sizing important when expectations are elevated.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. RBRK can react quickly to earnings, ARR growth, guidance changes, AI contracts and security-sector valuation shifts.
Top 5 Risks to Watch for Rubrik Investors in 2026
Rubrik has a growing recurring base, but durable per-share value depends on contract quality, cloud delivery costs and how quickly new AI security tools become paid subscriptions.
- Slower enterprise expansion would weaken future revenue. ARR assumes contract renewal; customer migration complicates underlying cloud-growth comparisons. Lower renewals or enterprise expansion would reduce future sales expectations before quarterly revenue visibly slows, weakening valuation support.
- Hosting costs can consume the benefit of scale. The quarterly filing reported a $7.9 million increase in hosting costs, and total gross margin declined. If workload infrastructure costs outgrow subscription pricing, incremental revenue creates less profit and supports a lower earnings multiple.
- Equity compensation dilutes the claim on future cash. Quarterly stock compensation reached $101.0 million from $88.5 million; weighted shares rose to 206.1 million from 194.9 million. Issuance can offset operating improvements when cash growth trails the share base.
- AI adoption may take longer to become paid growth. One-third customer usage establishes engagement; Code Guardian expands distribution. Neither disclosure supplies a separate recognized AI revenue total. Adoption without proportionate contract increases reduces returns on product development spending.
- A higher valuation magnifies execution disappointments. Shares gained 54.90% through October 13, placing more weight on continuing ARR expansion and cash generation. Reduced guidance can compress the multiple. Leverage amplifies the resulting price adjustment and potential capital loss.
Final Thoughts: Should You Invest in Rubrik in 2026?
Rubrik's strong recurring revenue growth reinforces its position in enterprise data security and cyber recovery, with Q2 subscription ARR rising 33% to $1.66 billion, adjusted EPS reaching $0.20, and free cash flow improving to $65.7 million. Expanding enterprise relationships and Agent Cloud partnerships offer additional growth opportunities as businesses invest in cyber resilience and AI-powered data protection. The key is whether stronger adoption can translate into higher contract values, improved margins, and sustained cash generation.
The $150 bull case depends on accelerating bookings, stronger AI monetization, and continued operating leverage, while the $90 bear case reflects slower growth and valuation pressure. The $110 to $130 base case assumes Rubrik delivers its current guidance with steady recurring revenue expansion. Investors can track upcoming ARR growth, Agent Cloud adoption, free cash flow guidance, and share dilution to assess whether improving fundamentals can support a higher valuation.
Risk Reminder: Investing in RBRK involves the risk of capital loss. Enterprise contract timing, infrastructure costs, AI monetization, stock-based compensation, and valuation changes can affect earnings and share-price performance. Investors should assess these risks and conduct independent research before investing.
Related Reading
- CrowdStrike (CRWD) Price Prediction 2026: Can AI Security and Falcon Flex Push CRWD Toward $280?
- Palo Alto Networks (PANW) Price Prediction 2026: Can AI Security Growth Push PANW Toward $475?
- Okta (OKTA) Price Prediction 2026: Can AI Agent Security Push OKTA Toward $225?
- UiPath (PATH) Price Prediction 2026: Can Agentic AI Push PATH Toward $23?
- Oracle (ORCL) Price Prediction 2026: Can AI Cloud Growth Push ORCL Toward $260?
